Abu Dhabi has become a very viable option for Indian
investors and NRIs, thanks to freehold ownership in the investment zones,
regulated off plan sales and staged payment options. It's a fairly simple
process once you know the order of the steps but Indian buyers have an
additional layer of complexity to deal with in the form of RBI remittance
rules, TCS (tax collected at source) and the annual tax return that you have to
file in India.
This guide walks you through the entire process using Sobha
City Abu Dhabi as the example. For the pricing and floor plans of the
project, see our Sobha City Abu Dhabi guide. For a comparison with the other communities in the market, check out Sobha City vs other Abu Dhabi master communities. You can also view the Sobha City Abu Dhabi property page.
Can Indians buy property in Abu Dhabi?
Yes. Since the real estate law in Abu Dhabi was amended in
2019, foreign nationals (including Indians) are now able to own freehold
property in the designated investment zones. Key points:
- No UAE residency or visa is required to purchase. A valid passport and the normal documentation for a
transaction is generally all that is required.
- Zones are important. Foreigners can only obtain
freehold in the registered investment zones (Yas Island, Saadiyat Island, Al Reem Island, Al Raha
Beach and Masdar City). The number of such zones has increased so you need
to check the status of your particular project.
- Check the project not just the area. Ask your advisor to confirm the ownership structure
(freehold, usufruct or musataha) of the particular unit you're looking at
prior to putting down a deposit.
Resident Indian v NRI: What's the difference?
Your status determines how you send money, whether you can
borrow and how you report the asset in India.
|
Factor |
Resident Indian (living in India) |
NRI (living abroad) |
|
Sending funds |
Through the RBI Liberalised
Remittance Scheme (LRS) |
Typically from NRE/overseas funds;
no LRS cap |
|
Annual cap |
USD 250,000 per person per
financial year (April to March) |
No LRS cap |
|
TCS on remittance |
Applies on property remittances
above the threshold |
Generally not applicable |
|
Borrowing abroad |
Restricted under FEMA without
specific approval; take advice first |
Non-resident mortgages possible
with UAE banks |
|
Reporting in India |
Foreign property must be disclosed
in Schedule FA of your ITR |
NRIs are generally exempt from
Schedule FA |
Rules are subject to change and individual circumstances
will vary. You should confirm your residential status and funding route with a
chartered accountant prior to making any remittance.
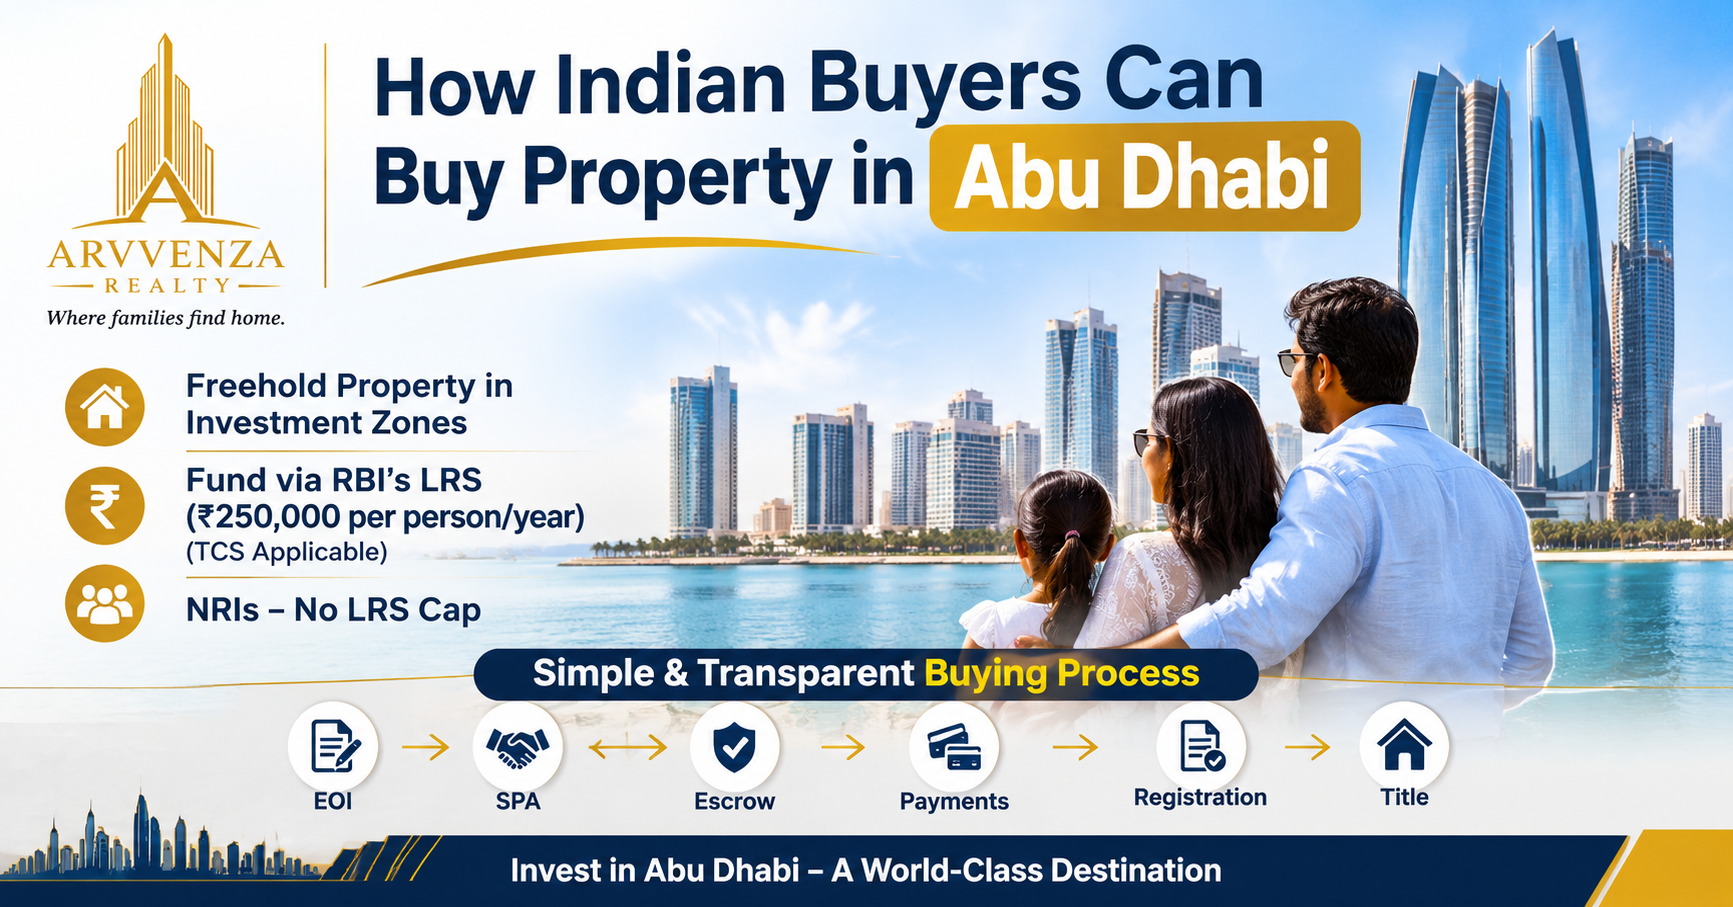
Step-by-Step: How to Buy Property in Abu Dhabi From India
1. Set your budget and funding route
Work out your total budget (including fees) and how the
funds will exit India (LRS, NRE or a combination of both). Staged payment is
useful in that you can remit in instalments.
2. Shortlist the project and developer
Check the developer's track record, the handover date and
the payment plan. Compare options across communities before narrowing down. Our
new project sales team can help you shortlist.
3. Register your Expression of Interest (EOI)
For new off plan launches ADREC now require EOIs to be
registered digitally via their Madhmoun platform with EOI funds held in a
government managed preparatory escrow account. Ask the sales team to show you
the EOI registration.
For Sobha City the listings report EOI amounts starting at
AED 35k for the one bedroom units and going up for the larger homes. Confirm
the current amounts and refund terms in writing.
4. Pay the booking amount and sign the SPA
After the EOI you pay the booking amount and sign the Sale
and Purchase Agreement (SPA). For Sobha City the plan is 20% on booking, 40%
during construction and 40% on handover in Q4 2029. Please read the SPA
schedule, delay clauses and default terms very carefully.
5. Pay into the project escrow account
Every off plan project in Abu Dhabi will have its own
regulated escrow account and your instalments must go into that account not to
the developer's account or to an agent's account. You need to check the escrow
details with the developer and the regulator.
6. Register your interest and handle the NOC
Off plan buyers get an interim registration certificate via
the DARI system. Abu Dhabi doesn't use Dubai's Oqood system. A developer NOC is
normally required prior to a subsequent transfer or resale.
7. Pay the final instalment at handover
The biggest payment (40% in the Sobha City plan) is due on
completion. Plan that payment well in advance and factor your LRS capacity into
that financial year.
8. Receive your title deed
Once the project is complete and the registration fee has
been paid, the title deed is issued and you can then go in to live in it, rent
it out or resell it.
Documents Indian Buyers Typically Need
- Valid passport (and visa pages where relevant)
- PAN card and Indian KYC documents
- Proof of address
- Source-of-funds proof (bank statements, salary slips,
ITRs)
- Signed reservation form and SPA
- Power of attorney, if someone signs on your behalf
- Mortgage pre-approval, if financing
Requirements will vary from project to project, bank to bank
and buyer to buyer so it's always worth asking for the developer's current
checklist.
Sending Money From India: LRS and TCS Explained
LRS. Each
resident individual may remit up to USD 250,000 per financial year
(April to March) for permitted purposes (e.g. purchase of property abroad). The
limit is per individual and applies to all LRS remittances (travel, education,
investment etc). Spouses and adult family members may each use their own limit.
You will normally complete Form A2 and use the appropriate purpose code with
your bank.
TCS on remittances for the purchase of overseas property is
20% above a threshold (in 2026 sources this is commonly cited as ₹10 lakh per financial year, older
articles refer to ₹7 lakh). TCS is an advance tax which you can generally claim
as a credit when you file your Indian return, though it does tie up your cash
for a number of months. Check with your bank or your CA to confirm the current
rate and threshold.
Illustration (TCS only):
if you remit ₹60 lakh in a financial year and the threshold is ₹10 lakh, TCS at
20% would apply to ₹50 lakh (i.e. ₹10 lakh).
Worked example: a Sobha City apartment priced at AED
1,350,000
The AED is fixed to the USD at circa 3.67 so the amounts
below are all illustrative using that rate.
|
Payment |
Share |
AED |
Approx. USD |
|
Booking |
20% |
270,000 |
73,500 |
|
Each construction instalment (8 in
total) |
5% |
67,500 |
18,400 |
|
Handover |
40% |
540,000 |
147,000 |
|
Total |
100% |
1,350,000 |
about 367,600 |
The total is in excess of one person's annual LRS limit but
the payments are spread across multiple financial years so each year's payment
can fall within the limit. A couple buying jointly can use two limits. The
trick is to work out which financial year each payment falls into and ensure
you have headroom prior to making the payment.
Other Costs to Budget For
- Registration fee is generally quoted as being around 2% of the price in Abu Dhabi. Who pays it and
is there a waiver from the developer?
- Agency or admin fees: will vary depending on the transaction.
- Service charges:
reported to be around AED 16 per sq.ft. for the apartments and AED 5 per
sq.ft. for the villas at Sobha City (check the current figures).
- TCS cash flow:
up to 20% on eligible remittances, held until you claim the credit.
- Currency:
AED is pegged to the dollar, the INR is not so your INR cost per
instalment can vary.
Can you get a mortgage in the UAE as an Indian buyer?
- NRIs and residents of the UAE can generally borrow from
UAE banks. The non-resident terms are more restrictive with loan to value
typically at 50%-60% and minimum property values often in the region of
AED 750k to AED 1m.
- Resident Indians:
FEMA restricts borrowing overseas without specific permission so the
majority of resident Indians will fund the purchase from their own pocket.
Get tax and legal advice prior to planning a UAE loan.
- Off plan: most banks will only lend on completed
properties so you need to check what the situation is before you go in
relying on the finance you have
at handover.
Golden Visa for Property Buyers
A property worth AED 2m or more will qualify an
investor for the 10 year Golden Visa. In Sobha City terms a 2 bedroom apartment
or a garden villa will be above the threshold in terms of price, a 1 bedroom
may not be.
Reports vary as to how off plan purchases, mortgages and
holding periods are dealt with in Abu Dhabi so it's essential to check the
current rules with the authority and your advisor prior to buying for visa
purposes.
Tax: What Indian Buyers Need to Know
- UAE:
no personal income tax on rental income or capital gains for individuals
(although you do pay service charges and fees).
- In India (both resident and ordinarily resident) your global income is taxable. The rental income from
the Abu Dhabi property will be taxed as house property income and as the
UAE has no personal income tax there is normally no foreign tax credit
available to offset it.
- Disclosure: a
resident and ordinarily resident taxpayer is required to report foreign
property on Schedule FA of the ITR every year, even if it is not
producing any rent. Failure to disclose can result in significant
penalties under the Black Money Act.
- NRIs are
generally only taxed in India on Indian sourced income and are exempt from
Schedule FA. The residential status rules are however very technical so
you need to check your own status.
This is general information only and not tax advice. You
should speak to a chartered accountant about your own circumstances.
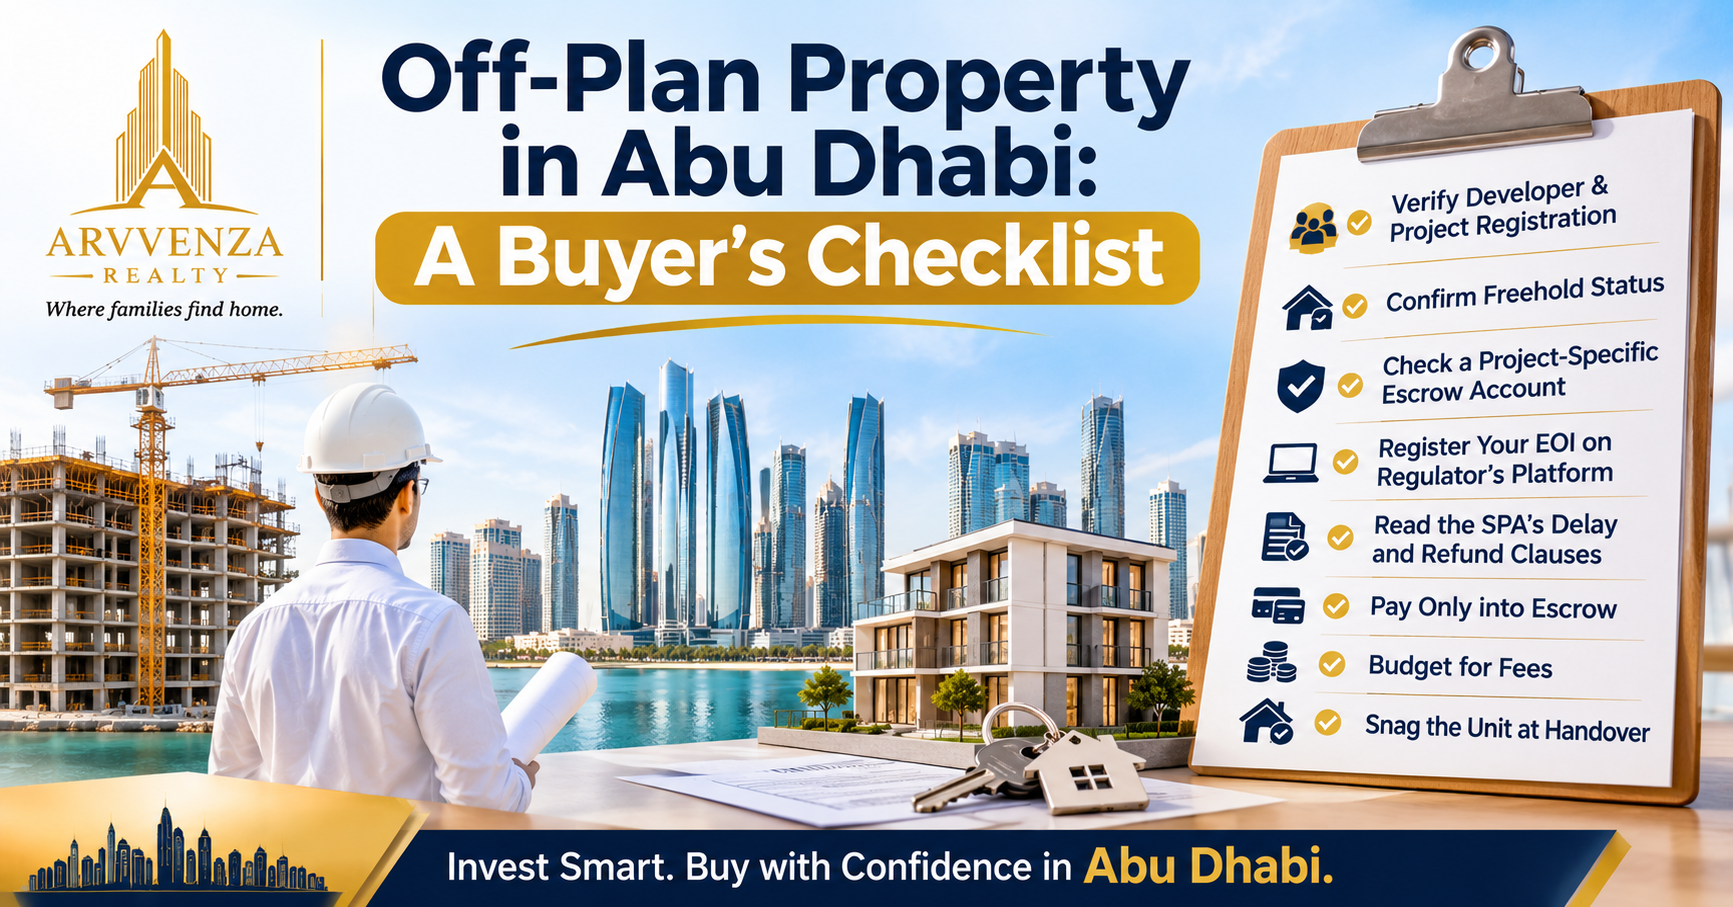
Safety Checklist Before You Pay
- Confirm the project is registered and has an approved
escrow account.
- Check the EOI is registered via the regulator's
platform.
- Pay only into the escrow account as named in your documents.
- Read the SPA for the delay, refund and default clauses.
- Just ask for the handover date, the estimate of service
charge and the payment schedule all in writing.
- Never pay a developer's instalment to an individual's
account.
- Keep every receipt and bank advice for your LRS and tax
records.
Common Mistakes Indian Buyers Make
- Treating the LRS cap as per transaction instead of per
financial year
- Forgetting TCS cash flow
- Not planning the large handover payment
- Skipping Schedule FA disclosure
- Assuming Dubai rules apply in Abu Dhabi
- Paying outside the escrow route
Talk to a Property Advisor
Our NRI and international property assistance team can walk you through virtual presentations, booking
steps and payment planning, and our real estate investment advisors can help you compare projects. You can also read our FAQ
page.
View Sobha City Abu Dhabi on our website | Talk to a Property Advisor
WhatsApp: +971-585512150 | Call:
+91-7051112002 (India) / +971-585512150 (UAE)
Share This Post